Set the candidate and ownership task first
Record original market, production configuration, battery, driven hardware and essential equipment. State planned distance, holding period and receiving location, including foreseeable changes in household or work use. The market-version dossier keeps another configuration’s data from silently entering the worksheet. Three years is a comparison boundary, not a required disposal date. Match the essential task between alternatives or label differences. Charging, receiving requirements and usable support remain acceptance gates; a low projected total cannot justify an unsuitable vehicle by omitting the access or preparation it needs. The owner should know which actual candidate and routine the calculation describes.
Carry the complete accepted acquisition boundary
Start with the dated landed-cost worksheet, retaining vehicle payment, understood preparation, transport and applicable receiving expenditure. Record currency, validity, inclusions and exclusions for each source. Obtain appropriate local advice for destination amounts instead of a universal tax estimate. Keep refundable items and financing schedules identifiable so acquisition is not counted twice. Where expenditure remains unconfirmed, retain a labelled alternative and the evidence needed to settle it. A FOB ask should not be compared with another offer’s ready-to-use total. The worksheet needs a clear starting amount the owner can explain before recurring energy and care are added.
Model purchased energy from usable replenishment
Use stated annual distance and credible route, load and climate assumptions. Keep purchased electricity, relevant session fees and charging-related parking on one consistent period boundary. The no-home-charging decision helps when public access dominates. A pack’s advertised capacity is not a charging bill, and a brochure cycle is not measured owner consumption. Assign installation and one-time equipment to setup rather than counting them again as recurring energy. Label planning inputs and replace them with supported observations when available. Retain an adverse charging-access case, not a hybrid fuel fallback, so the smaller estimated bill remains attached to a practical battery-electric routine.
Use applicable care and real receiving quotations
Review the identified vehicle’s instructions and accountable provider scope through the maintenance dossier. The arrival first-service review addresses the accepted initial condition. Include tyre, brake, auxiliary-battery or other operations when instructions or present evidence support their period relevance; do not invent replacement intervals. Retain insurance, parking and other local expenditure consistently between alternatives. Distinguish quoted correction from a contingency buffer. The buffer is a planning assumption, not proof that a named component will fail or that any consequential repair can be completed for that amount. Parts access and diagnosis uncertainty may affect usable ownership even when they cannot honestly be represented as a fixed cost line.
Keep disposal value uncertain and identifiable
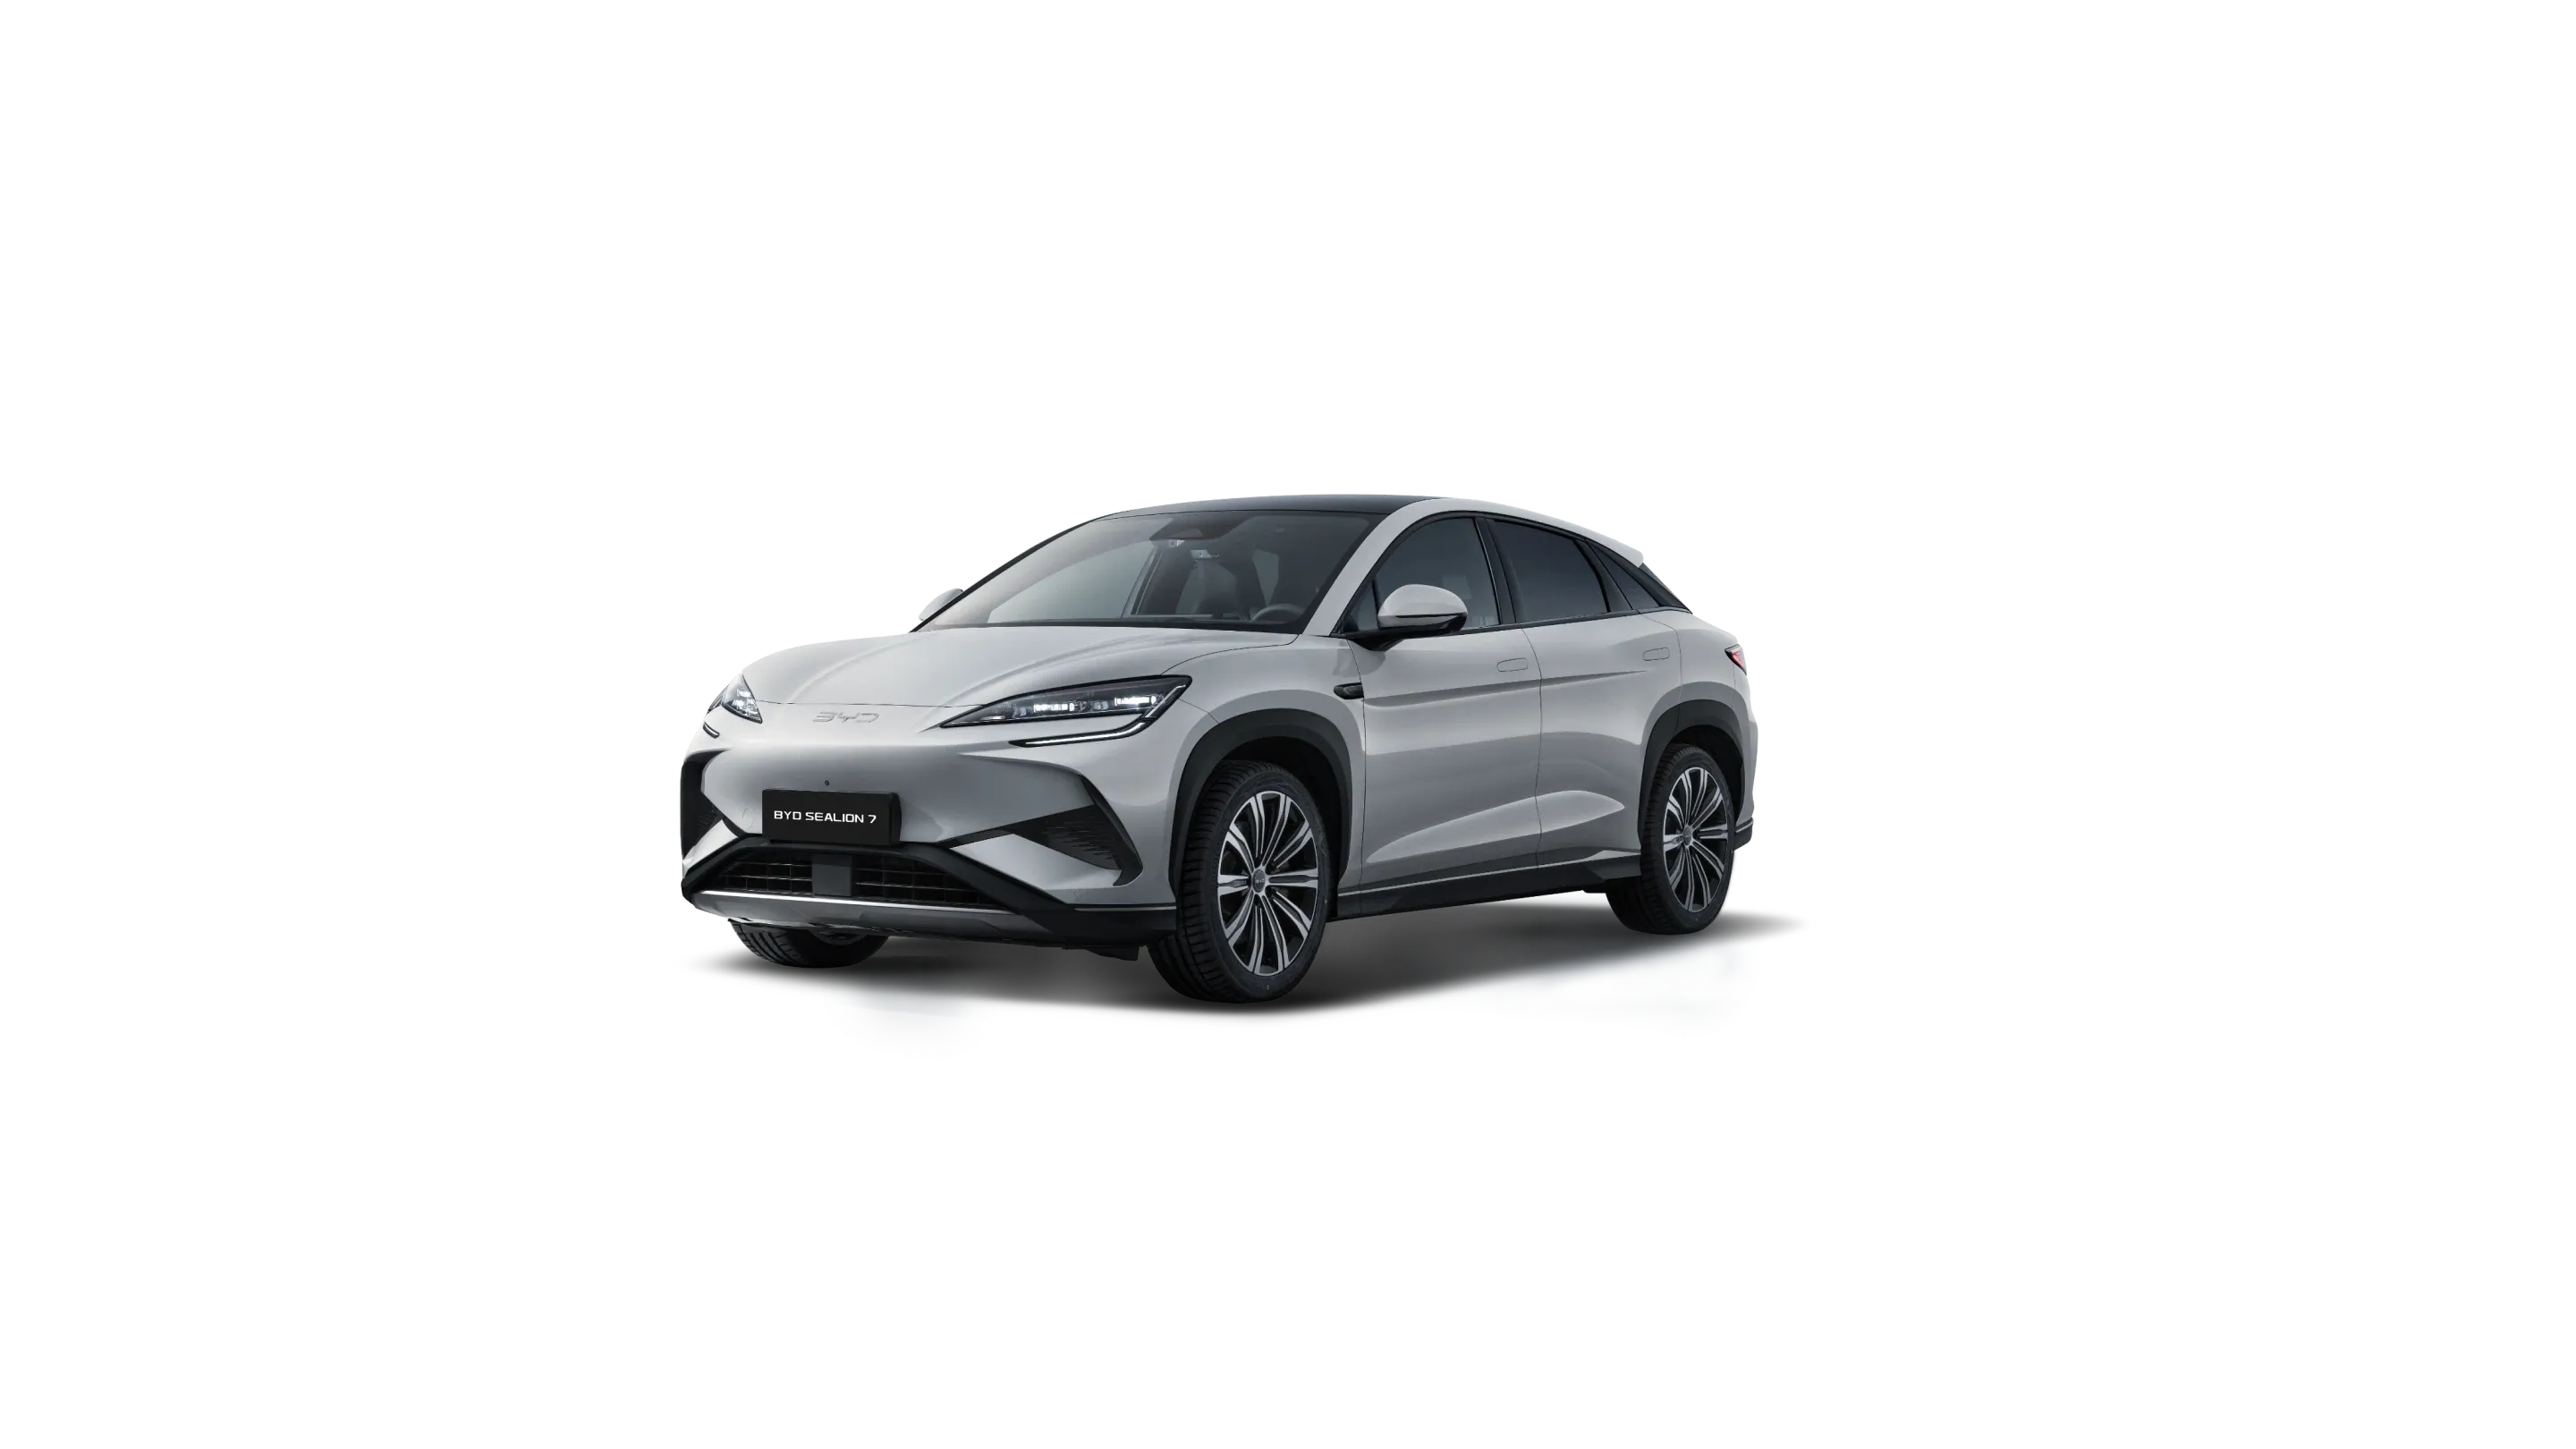
If a future receipt is part of the comparison, state its basis and test a less favourable case. Another market’s current advertised Sealion 7 is not a confirmed future sale value for this original configuration in the receiving location. Include relevant disposal expenditure consistently. The AWD premium review keeps a current repeated capability benefit separate from automatic resale recovery. A simple period total combines accepted acquisition and recurring outlays, then subtracts a labelled assumed disposal receipt. It is not an appraisal or investment return. Do not make a higher-priced candidate look guaranteed cheaper by selecting an optimistic figure whose market and condition basis cannot be explained.
Use sensitivity to expose the purchasing condition
Change distance, charging access, tariffs, defined preparation and disposal assumptions separately before combining a plausible adverse case. Explain what reverses the preference. The larger-battery premium review keeps useful margin separate from a capacity-based financial promise. If consequential diagnosis dominates the result, obtain evidence or another supported proposal rather than adding decimal precision to unknown amounts. Record agreed preparation and exclusions in the purchase schedule. Refresh after a changed VIN, destination or routine. The useful outcome is a transparent preference with acceptance conditions, not a polished total in which speculative future inputs have been mistaken for confirmed expenditure.